Myths and Facts About Insurance & Risk Management in Logistics
DY
Understanding Insurance in Logistics
Insurance plays a crucial role in the logistics industry, providing protection against potential risks and losses. However, there are several myths and misconceptions that can cloud understanding. It's important to separate fact from fiction to make informed decisions.
Myth: Insurance Covers All Types of Losses
One common myth is that insurance covers every possible loss or damage. In reality, insurance policies have specific terms and conditions. It's essential to read the fine print and understand what is covered and what is not. For instance, certain natural disasters or acts of war might not be included in standard policies.
Fact: Risk Management is More Than Just Insurance
While insurance is a vital component, risk management encompasses a broader strategy. It involves identifying potential risks, implementing preventive measures, and developing contingency plans. Effective risk management can minimize the likelihood of losses occurring in the first place.
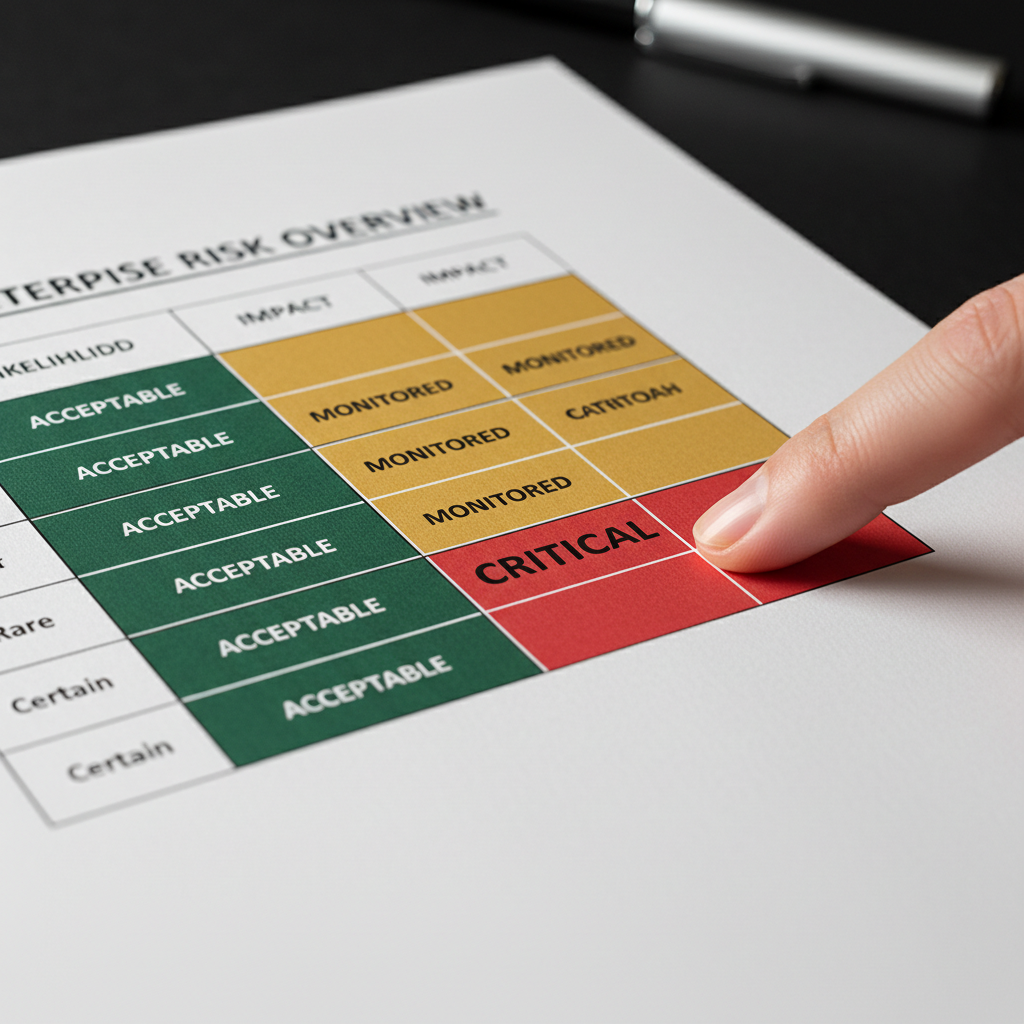
Common Misconceptions About Risk Management
Risk management in logistics is often misunderstood. Some believe it is only relevant to large companies, while others think it is too costly to implement. Let's address these misconceptions.
Myth: Small Businesses Don't Need Risk Management
Many small business owners assume that risk management is only necessary for large corporations. However, small businesses can be just as vulnerable to risks. Implementing a risk management strategy can safeguard operations and provide peace of mind.
Fact: Risk Management Can Be Cost-Effective
Contrary to popular belief, risk management doesn't have to be expensive. By assessing risks and prioritizing actions, businesses can implement cost-effective solutions. Investing in risk management can ultimately save money by preventing costly disruptions and losses.
Practical Steps for Effective Risk Management
To develop a robust risk management strategy, businesses should follow a structured approach. Here are some practical steps to consider:
- Identify potential risks specific to your logistics operations.
- Evaluate the likelihood and impact of each risk.
- Implement preventive measures to mitigate identified risks.
- Regularly review and update risk management plans.
By understanding the myths and facts about insurance and risk management, businesses can better protect their logistics operations against unforeseen events. This proactive approach not only safeguards assets but also enhances overall operational efficiency.